Kara-Vimukti: Tax Exemptions and Incentives
Strategic Non-Taxation
Kautilya understood that sometimes the best tax policy is not to tax at all. His framework for exemptions, protecting the vulnerable, encouraging development, and rewarding service, reveals sophisticated fiscal thinking that modern policymakers continue to employ.
The Empty Treasury That Built an Empire
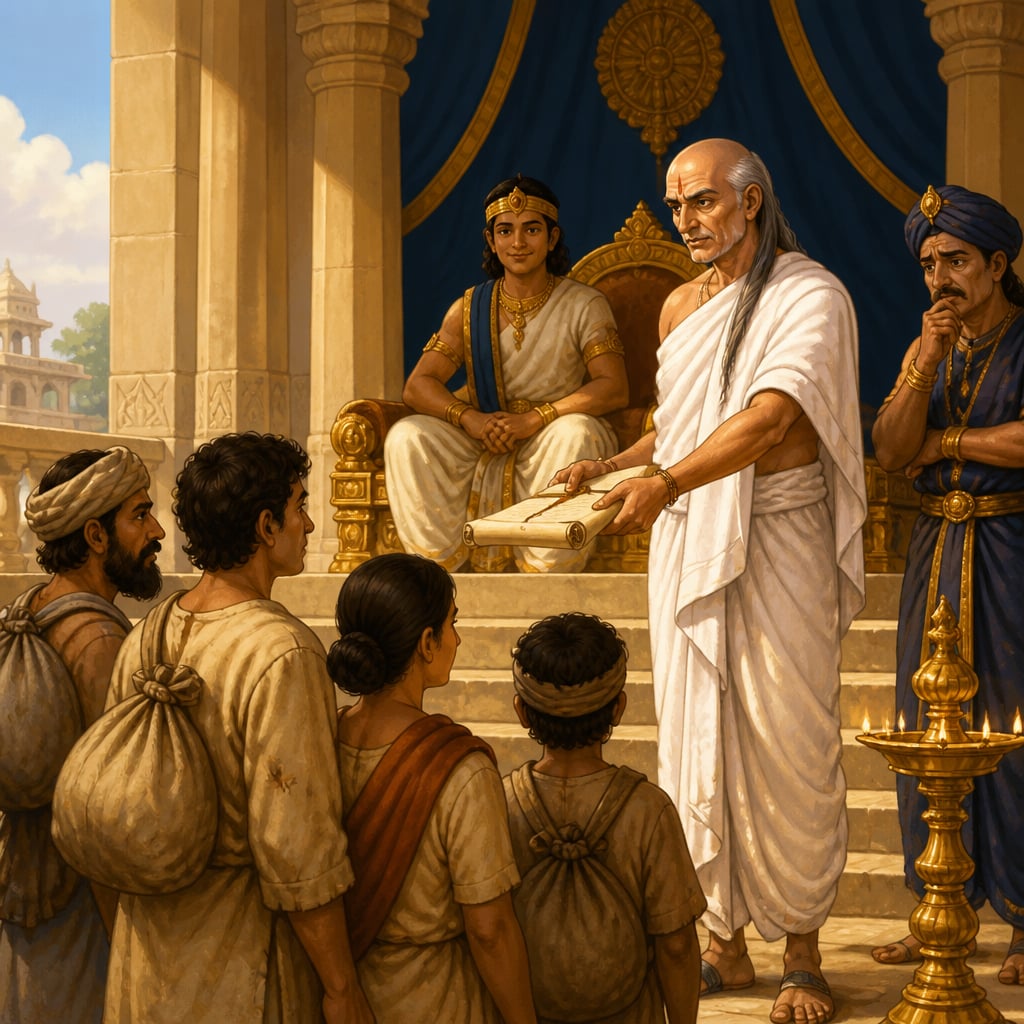
In 318 BCE, a delegation of settlers approached the Mauryan court with an unusual request. They wanted to clear and cultivate a stretch of dense forest near the Vindhya foothills. The land was wild, unpopulated, and produced no revenue. Cultivating it would require years of backbreaking work with no guaranteed success.
Kautilya's response surprised many courtiers: "Grant them the land free of tax for seven years."
The treasury minister protested. How could the state afford to forgo revenue? But Kautilya saw further. In seven years, that empty forest would become productive farmland. The settlers would have families, build villages, create markets. After the tax holiday expired, the state would collect far more than it ever could from wilderness.
This was Kara-Vimukti (कर-विमुक्ति), tax exemption as strategic investment.
The Logic of Non-Taxation
Kautilya's exemption framework wasn't random charity. It followed careful principles that modern economists would recognize as fiscal incentives.
"विमुक्तेर्वृद्धिः भवति।"
"From exemption comes growth." , Arthashastra 2.1
The logic: Some activities generate more value untaxed than taxed. A farmer who keeps his entire first harvest can reinvest in better tools, clear more land, and hire workers. In five years, he pays more tax from a larger operation than he would have if taxed from the beginning.
Kautilya identified several categories deserving exemption:
Developmental Exemptions:
- New land cultivation (typically 2-7 years tax-free)
- Irrigation projects (exemption during construction)
- Manufacturing establishments (startup period protection)
- Mining and mineral extraction (initial investment recovery)
Social Protection Exemptions:
- The destitute and disabled (permanent exemption)
- Students and scholars (during study period)
- Religious establishments (temples, monasteries)
- Widows and orphans (until self-sufficient)
Service Recognition Exemptions:
- Military personnel and families
- Government servants on fixed salaries
- Brahmins performing rituals (in exchange for dharmic services)
- Villages that provided security services