Bali: The Ethics of Tax Collection
From Sacred Offering to State Revenue
The ancient concept of Bali, voluntary tribute offered to protect dharma, shaped how Indians understood their relationship with the state. Kautilya transformed this sacred concept into practical administrative ethics.
The King's Portion and the Citizen's Faith
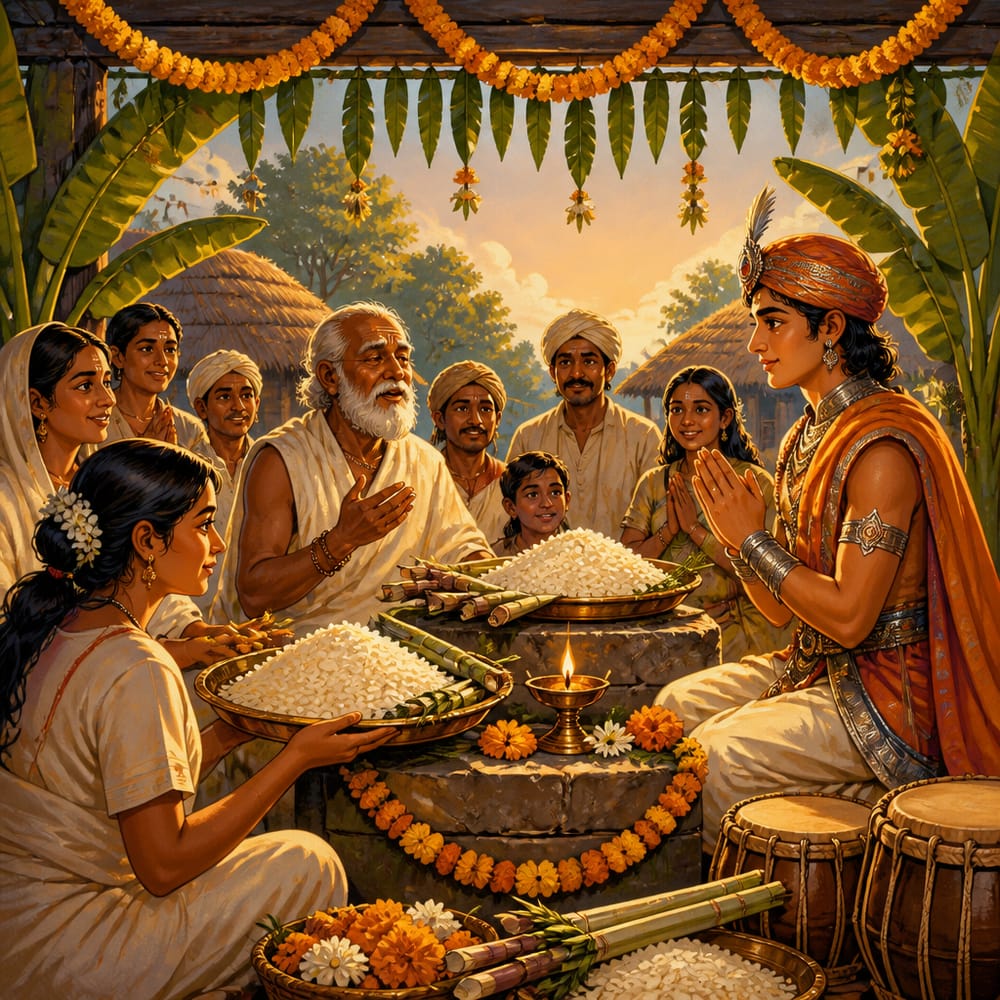
In the ancient village of Vaishali, the harvest festival was more than celebration. As farmers gathered their grain, they set aside a portion, not grudgingly extracted, but voluntarily offered. This was Bali (बलि), the tribute given to the king who protected their fields, settled their disputes, and maintained the irrigation channels.
Bali was different from Bhaga (the mandatory share) or Shulka (customs duty). It was not extracted by force but offered in recognition of services rendered. The king who received Bali accepted a sacred trust: to use these resources for the people's welfare.
Kautilya understood this ancient compact. The Arthashastra preserves the ethical dimension of taxation even while systematizing its administration.
The Threefold Revenue Framework
Kautilya distinguished three categories of state revenue, each with different ethical implications:
Bhaga (भाग) - The Mandatory Share:
- Fixed proportion of agricultural produce (typically 1/6)
- Collected regardless of the payer's willingness
- Justified by the state's role in providing security and infrastructure
- The closest ancient equivalent to modern mandatory taxes
Shulka (शुल्क) - Transaction Duties:
- Fees on specific activities (trade, mining, manufacturing)
- Payment for permission to engage in regulated activities
- More like user fees than general taxation
Bali (बलि) - Voluntary Tribute:
- Offerings made in recognition of the king's dharmic role
- Traditionally associated with protection and justice
- Could include special contributions during emergencies
- Carried strong expectations of reciprocal duty
The crucial insight: even "voluntary" Bali came with obligations. A king who accepted tribute but failed to protect, who collected but did not serve, violated dharma itself.
The Tax Collector's Dharma
Kautilya devoted significant attention to how revenue should be collected, not just what amount. The manner of collection was itself a dharmic matter.
"समाहर्ता धर्मेण कोशं समाहरेत्।"
"The revenue collector shall gather the treasury according to dharma." , Arthashastra 2.6.1