Lekha: Ancient Accounting and Audit Systems
When Every Coin Told a Story
Kautilya understood that revenue collected without accountability disappears into corrupt pockets. His elaborate accounting systems, multiple ledgers, cross-verification, independent audits, created transparency centuries before double-entry bookkeeping reached Europe. From Mauryan accountants to the CAG, the principle endures: what gets measured gets managed.
The Missing Elephants
In the third year of Ashoka's reign, a troubling report reached Pataliputra. The royal stables in Taxila claimed to house 500 war elephants, yet when the king's inspector arrived, he counted only 412. Eighty-eight elephants had vanished from the ledgers.
Akshapataladhyaksha Vrishala, the Chief Accountant, was summoned. This wasn't merely theft, it was a systemic failure. Elephants weren't coins that could slip through fingers; they were massive animals requiring handlers, fodder, and stables. If 88 elephants could disappear, what else was leaking from the empire?
Kautilya had anticipated exactly this problem. His solution was comprehensive: not just counting, but cross-verification; not just records, but audits; not just punishment for fraud, but systems designed to make fraud visible.
The Lekha System: Architecture of Accountability
The term lekha comes from the Sanskrit root 'likh' (to write/record). But Kautilyan accounting was far more sophisticated than simple record-keeping. The Arthashastra mandates:
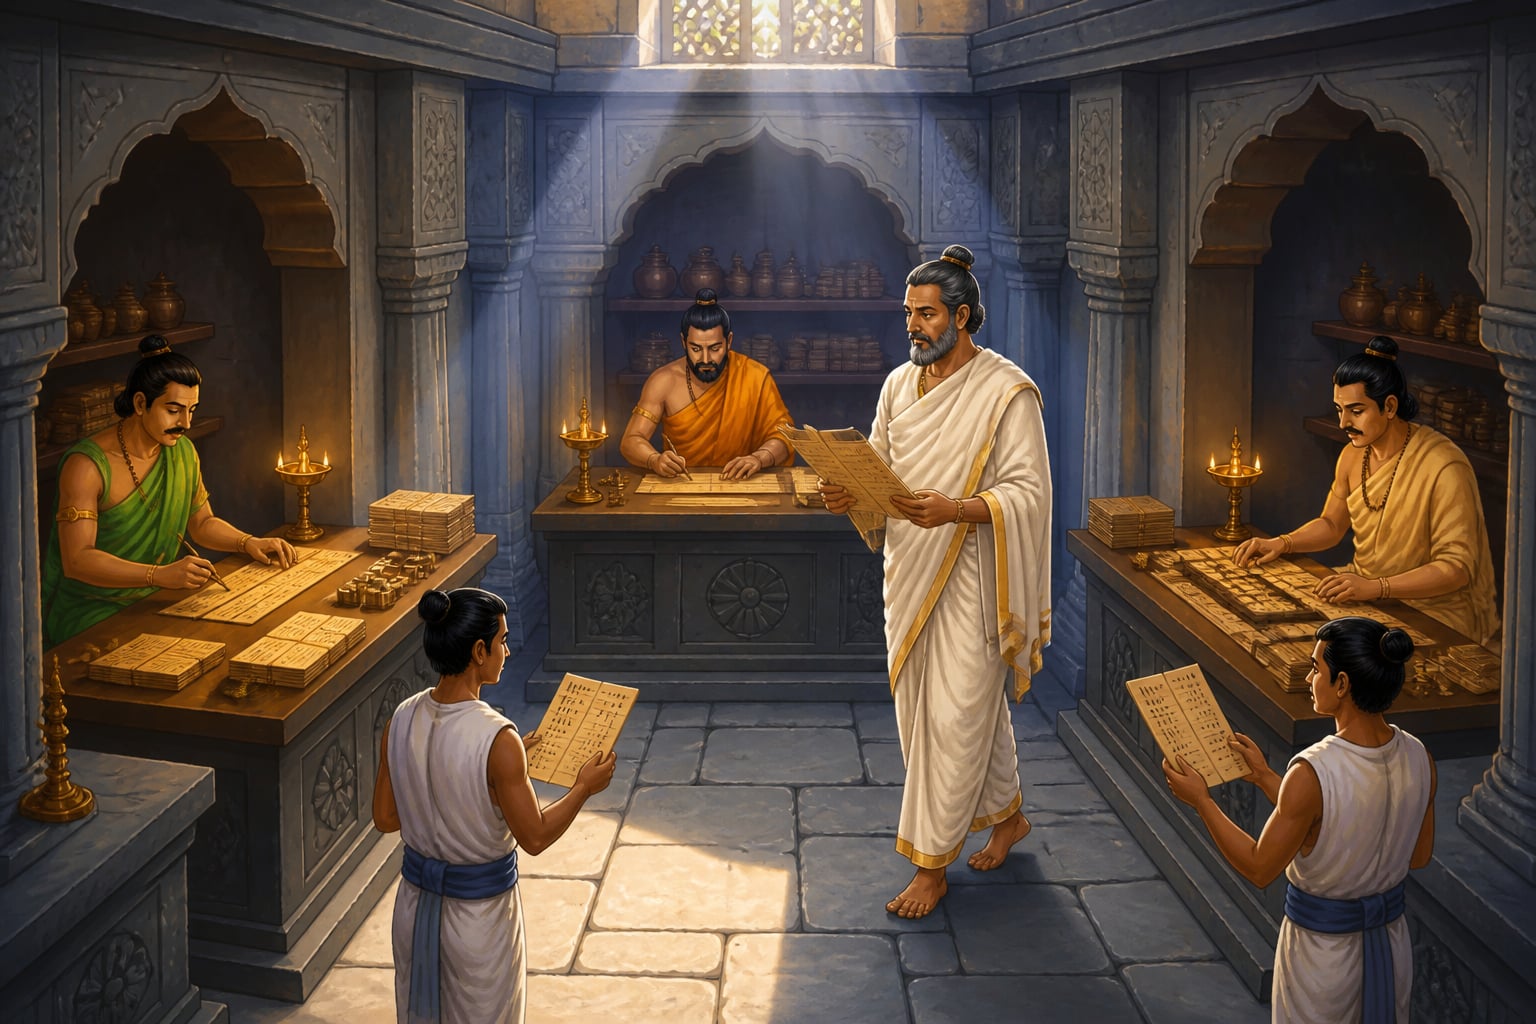
Multiple Parallel Records:
- The Samaharta (Revenue Assessor) maintained income estimates
- The Sannidhata (Treasurer) tracked actual collections
- The Akshapataladhyaksha (Accountant General) verified both against each other
No single official controlled both recording and custody. This separation, what modern auditors call "segregation of duties", made collusion necessary for fraud, dramatically increasing detection probability.
"Let accounts be submitted daily. Let the accountant cross-verify. Let the auditor examine independently." , Arthashastra 2.7
Standardized Documentation: Kautilya specified exactly what every transaction record must contain:
- Date and time
- Names of parties involved
- Nature of transaction
- Quantity and quality of goods
- Authorization signatures
- Witness verification
This standardization wasn't bureaucratic fetish, it created audit trails. When discrepancies appeared, investigators could trace exactly where the record chain broke.
Regular Reconciliation: The Arthashastra mandates daily, monthly, and annual reconciliations:
- Daily: Cash collections versus recorded receipts
- Monthly: Inventory counts versus ledger balances
- Annual: Full audit by independent inspectors