Relevance in 2026 and Beyond
From Digital Hundi to Global Standard
How India's UPI Revolution and Digital Public Infrastructure model is reshaping global finance, from G20 adoption to cross-border payments, and what it means for financial inclusion worldwide.
Relevance in 2026 and Beyond: From Digital Hundi to Global Standard
A Transaction in Singapore
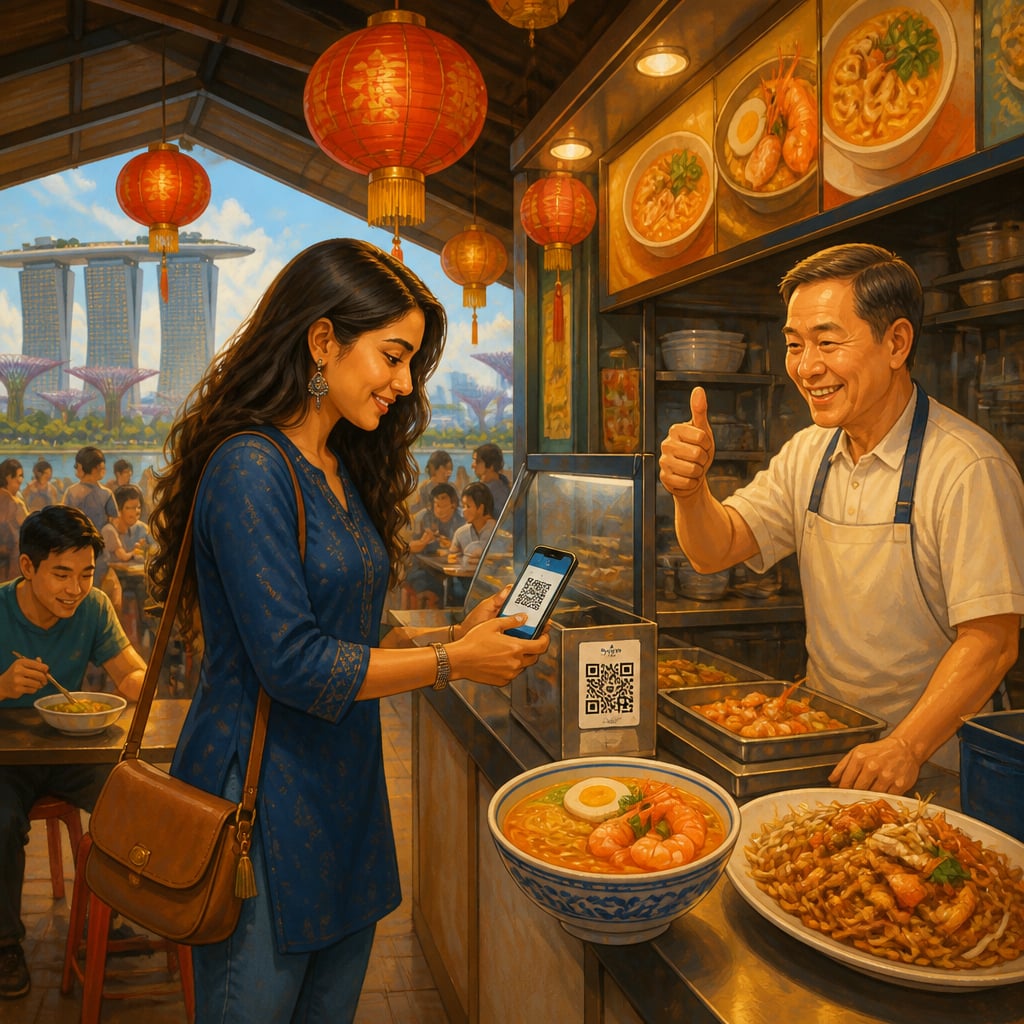
In February 2024, a tourist from Mumbai walks into a hawker center in Singapore. She sees a sign she recognizes, a QR code with the UPI logo. She scans it with PhonePe, enters the amount in rupees, and the Singapore vendor receives payment in dollars. Instantly. No intermediary bank. No forex counter. No 3% Visa fee.
Five years ago, this was impossible. Today, it's a glimpse of the future, a future where India's digital payment rails are becoming a global standard, and where Dharmic principles of trust, interoperability, and public good are reshaping how the world moves money.
But this isn't just about technology. It's about a fundamental question: Can developing nations set global standards? Can ancient principles of collective welfare outcompete profit-maximizing platforms?
The Global Challenge: Fragmented, Expensive, Exclusionary
The global payments system in 2024 remains remarkably broken.
Cross-border remittances cost an average of 6.2% globally, meaning migrant workers sending $500 home lose $31 to fees. For Africa, it's worse: 8.5% average, with some corridors exceeding 20%. The World Bank's target of 3% by 2030 looks increasingly unrealistic.
Small merchants worldwide remain dependent on Visa and Mastercard, paying 2-3% on every transaction. For a restaurant with 5% margins, this fee consumes 40-60% of their profit. In developing nations, these fees push merchants into cash-only operations, keeping them invisible to the formal economy.
Financial exclusion persists despite decades of effort. 1.4 billion adults globally remain unbanked. Even among the banked, 3 billion lack access to meaningful credit. The traditional banking model, brick-and-mortar branches serving customers with stable incomes and collateral, cannot reach them economically.
Meanwhile, Big Tech is moving into finance. Apple Pay, Google Pay, and various fintech "super apps" promise convenience but replicate the old model: private control of rails, data extraction, and rent-seeking. The platform, not the user, captures most of the value.