Relevance in 2026 and Beyond
Reclaiming Financial Sovereignty Through Digital Innovation
How India's journey from colonial financial subjugation to UPI's global leadership offers lessons for economic sovereignty, financial inclusion, and the future of banking.
Modern Hook: Your Phone Is a Revolution
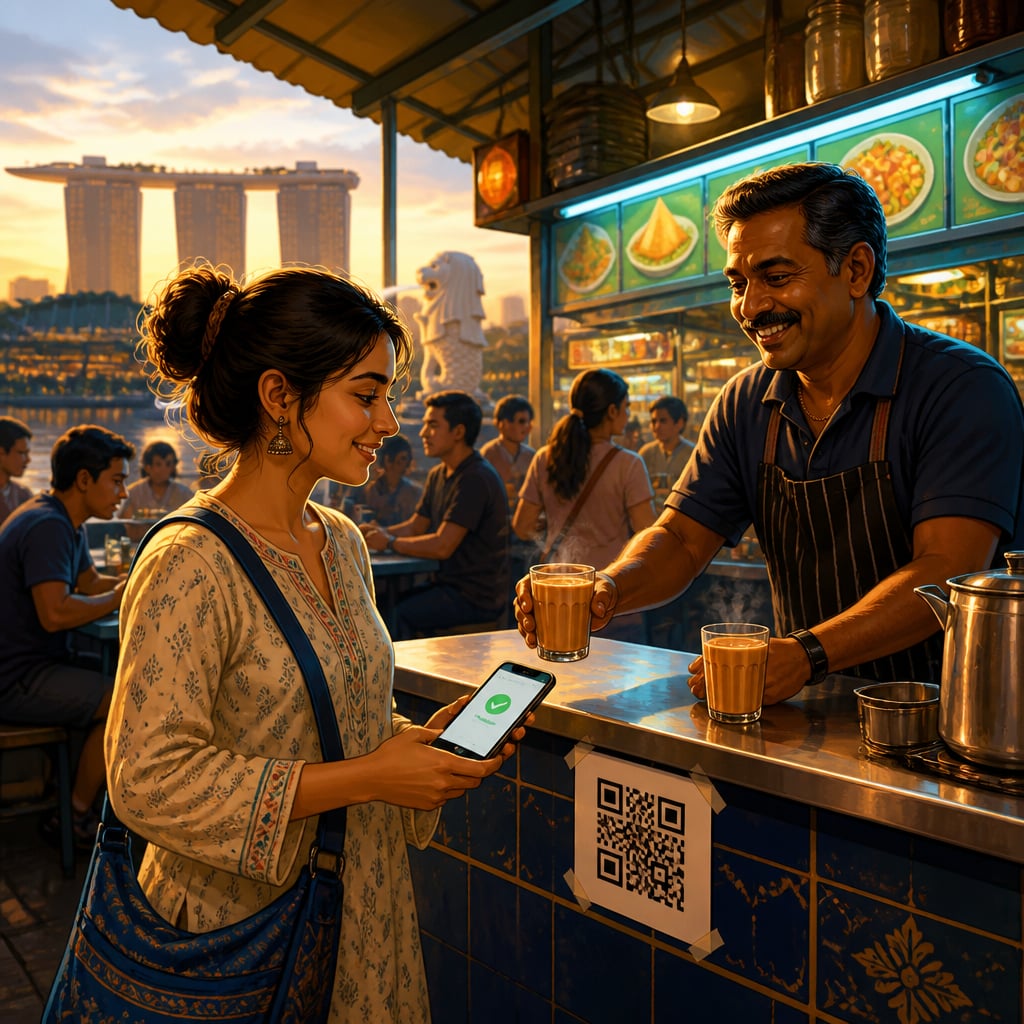
You're at a street vendor in Singapore, buying chai. You scan a QPI code, India's UPI protocol, now operating internationally. The transaction completes in 2 seconds. No Visa. No Mastercard. No fees going to Western payment networks.
This unremarkable moment represents something extraordinary: an Indian-built payment system, developed by Indian engineers, governed by Indian regulations, processing transactions across borders. For the first time since the East India Company arrived in 1608, Indian financial infrastructure is being exported rather than imported.
How did a nation whose indigenous banking systems were systematically dismantled over 200 years become a global leader in digital payments? And what does this reversal teach us about economic sovereignty in the 21st century?
The Modern Challenge: Financial Colonialism 2.0
The colonial playbook hasn't disappeared, it's evolved. When Visa and Mastercard dominated India's card payments in 2015, they extracted interchange fees on every transaction. American tech companies set terms for digital wallets. Swift, the Belgian-based messaging system, controlled international remittances.
This wasn't military occupation, but the effect was similar: value extraction flowing outward, decision-making power located elsewhere, dependency built into the financial architecture.
The stakes are significant. In 2024, India processes over 14 billion UPI transactions monthly, approximately $250 billion in value. Had this remained on Western payment rails, billions in fees would flow abroad annually. More importantly, foreign corporations would control the data infrastructure underlying India's commerce.
Globally, similar dependencies persist. African nations send $48 billion in remittances annually through Western Union and similar services, losing 6-9% to fees. Southeast Asian economies depend on Singapore and Hong Kong as financial intermediaries. The infrastructure of money remains concentrated in a handful of countries.
The Ancient Insight: What the Chapter Taught Us
The preceding lessons revealed a pattern: India possessed sophisticated indigenous banking systems that were deliberately dismantled, then rebuilt according to colonial needs, and finally reclaimed through deliberate national effort.